By
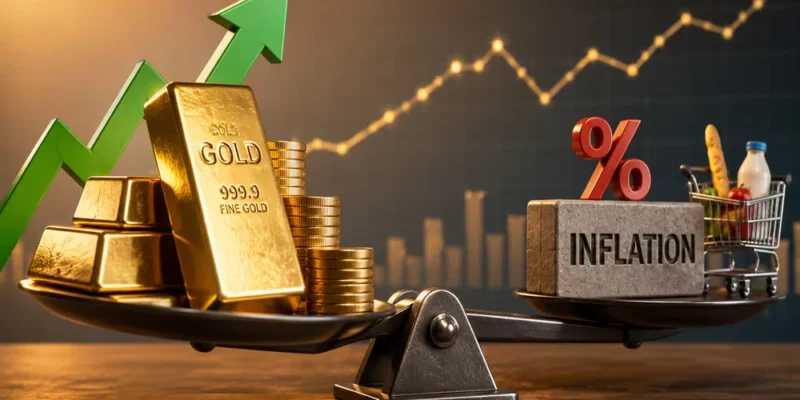
Prices of vegetables, school fees, medical care, and housing rarely move backwards, and Indian families feel this pressure every month when the household budget is drawn up. It is one reason why so many people keep a close eye on the Today Gold Rate, treating the metal as a quiet guardian of their savings. Someone in the twin cities scanning Gold Rate Today Hyderabad may be looking for a buying opportunity, but the deeper motivation is often protection: the hope that wealth stored in gold will keep its purchasing power when everyday costs climb. Is that hope justified? The honest answer is nuanced. Gold has served as a store of value for centuries, yet it is neither a guaranteed hedge nor a substitute for a well-rounded financial plan. This article examines what gold can and cannot do for a household worried about rising prices.
How Inflation Erodes Household Savings
Inflation is a slow and steady rise in prices, which steadily eats away at savings. Money lying idle in a savings account with a low interest rate may appear to be secure, but if prices rise faster than the rate of interest, then the value of money decreases every year. A family that has been saving a lakh of rupees for a decade now finds that the same amount will get them far fewer goods and services than it would have ten years ago. This is a worry for families that need to fund a child’s education, a daughter’s marriage, or their own retirement, as the cost of these is set to rise considerably by the time they need the money. Financial planners argue that the family must think of ways to grow their savings faster than inflation, or else they will be steadily poorer over time, even if the account balance grows. The quest for assets to help protect wealth against the erosion of inflation leads many to gold, which has a long history as a store of value.
Gold’s Long Record as a Store of Value
For long stretches of history, gold has outlasted many paper currencies and proved a better store of value for those who hold it. Gold has appreciated steadily over decades in India, and those who have held on to it over time have seen their wealth grow, in many cases, at a faster rate than the increase in prices. There are several factors that contribute to gold’s reputation as a hedge against inflation. Gold has a fundamental scarcity value, is sought after globally, and has value in and of itself, not tied to any particular government or entity. During times of economic uncertainty, gold tends to hold its value better and often rises in price against other assets, providing an inflation hedge. Gold has also done well historically in India, due to the rupee’s proclivity to depreciate against other currencies. A weaker rupee makes imported items more expensive, and since gold is an internationally traded item, its price in India rises during such periods. However, gold has also seen periods where it has risen steadily for a few years, then stagnated or declined for several years in succession. Those who bought gold at the peak prices of 2013, for example, would have needed to patiently hold on to it for years for their investments to pay off. Gold as an inflation hedge, therefore, must be considered in the long term.
Building a Balanced Allocation
Due to gold’s unique position as an inflation hedge, it provides good diversification for a family that wishes to balance their portfolio between growth and security. When the stock market falls, gold has often risen, and vice versa. Many financial planners advise a modest allocation to gold as a hedge against market fluctuations, with a common recommendation being between five to fifteen per cent of one’s portfolio in physical gold, depending on individual circumstances. The rest can be divided between equities and fixed deposits, depending on the family’s risk tolerance and requirements. Those who already have considerable jewellery as part of their gold allocation, for personal adornment and use, might consider this to be their gold holding, and balance it out with other assets. Gold should be bought periodically, in smaller instalments, to take advantage of price fluctuations, and avoid buying at market peaks. It is best to balance gold with emergency reserves and insurance, as gold should not be considered as part of a family’s liquid assets.
The Limits of Gold as an Investment
While gold has many advantages to offer, it is important to consider its limitations as an investment. Gold does not offer any returns in the form of income, and therefore its value is purely in appreciation. Physical gold also comes with expenses, such as storage and making charges in the case of jewellery, which can further reduce profits if the jewellery is sold at a loss. Gold prices are also highly volatile in the short term, and those who need liquid cash during a market dip will find themselves in a difficult position if they have to sell their gold at a loss. Gold also cannot provide the same long-term gains as investments in productive assets, such as well-managed equities, which can steadily generate wealth over time. The value of gold as an inflation hedge must also be balanced with a realistic perspective; gold should be seen as insurance against inflation, and not as an end in itself, or a replacement for other well-managed investments. Gold can be a part of a larger investment strategy, but not the sole one.
Gold can be a valuable addition to a family’s investment portfolio, as it has proven to be a good hedge against inflation, and can provide diversification and security, especially in the long term. Gold should be considered as a part of a balanced investment strategy, in combination with other assets such as equities and fixed deposits, and with due caution as to not overestimate its capacity as an inflation hedge.